Scotland’s Stopgap Plan Exposes Ferguson Yard’s Strategic Crossroads
Scotland is preparing interim work to keep Ferguson Marine active after completion of its final current vessel, highlighting the tension between preserving sovereign shipbuilding capacity and confronting weak commercial competitiveness. For operators and owners, the case illustrates how yard reliability, delivery risk and retrofit execution have become more valuable as regulatory costs tighten across Europe.
What happened
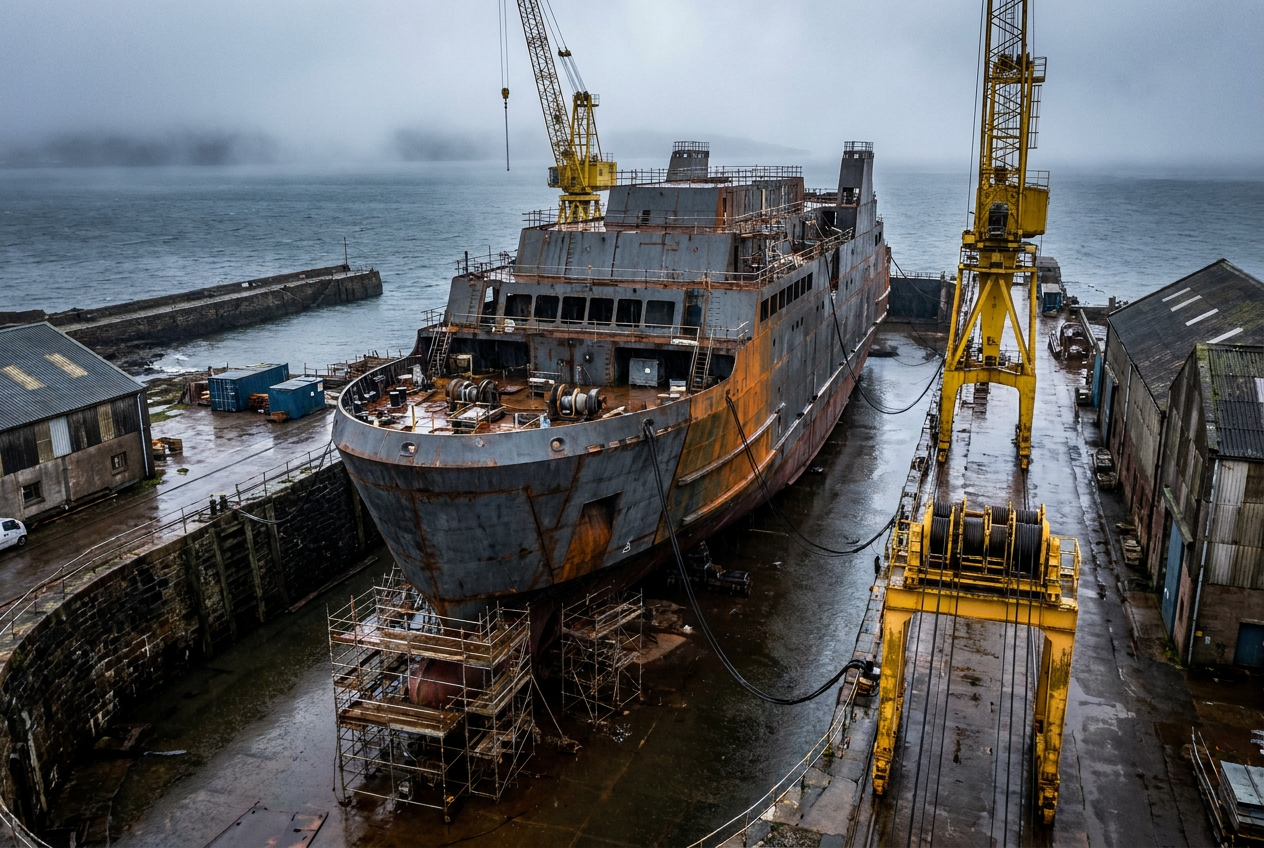
The Scottish government has moved to sustain operations at the state-owned Ferguson Marine yard near Glasgow as it nears completion of the ferry Glen Rosa, the last vessel presently in its orderbook. Ministers said the yard may receive funding to construct tugboats before any buyers are secured, potentially using an established external design partner, while the workforce is also being reduced through voluntary departures. The announcement follows years of delay and rising costs on the dual-fuel ferry program and renewed criticism from political opponents over the lack of firm new contracts.
What it means for owners
For shipowners and operators, the Ferguson situation is not just a regional industrial story; it is a reminder that execution certainty at yards now has direct earnings implications. In today’s market, late delivery or prolonged yard periods are more expensive than they were even five years ago. Vessels face tighter compliance pressure from carbon-intensity rules, EU ETS exposure on relevant voyages, and FuelEU Maritime compliance trajectories that sharpen the economics of fuel choice, technical upgrades and time in service. Every month of delay can mean deferred charter revenue, extended use of older tonnage with weaker CII performance, or a missed window to introduce lower-emission assets into a fleet plan. For ferry operators in particular, operational reliability matters as much as design ambition: a vessel intended for cleaner fuel but trading on conventional fuel because of unresolved technical issues weakens both the environmental case and the expected total-cost-of-ownership case.
The proposal to build tugboats on speculation also speaks to a wider capacity mismatch in Europe’s repair and newbuild ecosystem. Owners need dependable slots for steel renewal, propulsion upgrades, energy-saving devices, battery integration, alternative-fuel retrofits and class-driven life-extension work. Yet smaller yards often struggle to secure enough pipeline visibility to retain skilled labor, while larger yards prioritize higher-value contracts or defense work. That creates a difficult middle ground: operators need flexible regional yards, but those yards need repeatable products and disciplined project management to survive. A standardized tug platform from an experienced design house could reduce engineering risk and compress build learning curves, which is sensible in principle. However, speculative construction changes the risk transfer. Instead of a buyer carrying some market timing risk through a contract, the yard and ultimately the public balance sheet carry inventory, financing and remarketing risk.
There is also a strategic lesson here about retrofit economics versus bespoke shipbuilding. In a market shaped by compliance costs, many owners are increasingly cautious about highly customized tonnage unless route economics, port infrastructure and subsidy frameworks are clear. Standardized harbor craft and workboats can be more bankable because they are easier to place, class, maintain and remarket. But success still depends on cost discipline, supply-chain control, and aftersales support. For operators assessing where to place future work, Ferguson’s recent history will inevitably raise questions about schedule assurance, systems integration capability and the yard’s ability to support modern propulsion packages without prolonged troubleshooting. In an era when off-hire can erase the benefit of an efficiency upgrade, the commercial value proposition of any yard now rests less on patriotic or political considerations and more on predictable delivery, class-compliant quality and lifecycle support.
MaritimeNG — critical view
The Scottish government’s intervention may be understandable from an industrial-policy perspective, but speculative vessel building is a high-risk substitute for a real market strategy. If there is no anchored customer demand, the yard could finish with completed assets that are slow to sell, tying up cash and labor while doing little to rebuild confidence. That may preserve employment in the near term, but it does not necessarily create a durable competitive position.
There is also a credibility problem. A yard that has suffered severe delay and cost escalation on a flagship program needs more than bridge financing; it needs visible governance reform, transparent milestones, and a convincing commercial focus. Without that, the stopgap approach risks being seen as postponement rather than restructuring. Political arguments about maintaining the last Clyde shipyard have weight, but sentiment alone will not overcome scale limits, procurement weakness or persistent execution concerns.
Verdict
Scotland’s plan may buy Ferguson Marine time, but time is only valuable if it is used to restore delivery credibility and define a realistic niche in standardized, supportable vessel work. For owners and operators, the episode reinforces a simple procurement rule: in a tighter regulatory and off-hire environment, yard reliability is now as important as headline build price or green design intent.
Fundamental basis
The economic mechanics behind the facts above, grounded in Martin Stopford’s Maritime Economics. Reference only — not investment advice.
Facing a similar situation on your vessel? Model the numbers before you commit.
Open the off-hire & deviation calculatorsSource Attribution
This analytical review is based on publicly available facts originally reported by The Maritime Executive. MaritimeNG does not claim authorship of the underlying facts. Read the original publication
© 2026 MaritimeNG — Independent analytical commentary. All analysis, opinions, and forward-looking assessments are original work by MaritimeNG Editorial and may differ from those of the parties mentioned or the cited source. Factual data is restated in our own words based on publicly available information. All trademarks and trade names belong to their respective owners. This content does not constitute legal, technical, or investment advice.