Navigator Gas Deepens Ethane Retrofit Bet After Eight Years of Proven Service
Navigator Gas’s decision to convert two more gas carriers to ethane-capable propulsion signals growing confidence in cargo-driven fuel strategies rather than full fleetwide fuel switching. For shipowners, the move highlights how targeted retrofits can improve voyage economics and emissions performance on specialised trades without committing to newbuild replacement.
What happened
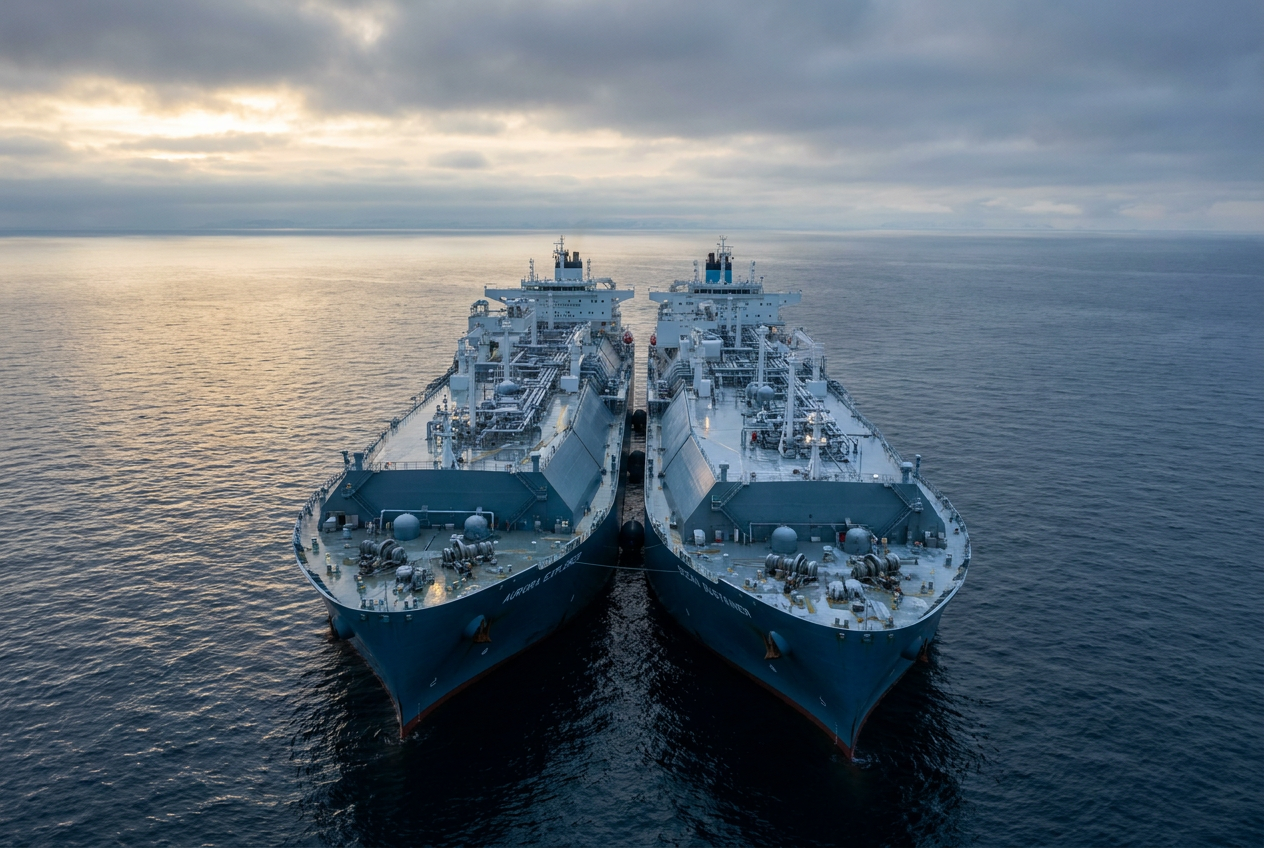
Navigator Gas has placed a follow-on order with Everllence PrimeServ to modify the main engines on Navigator Nova and Navigator Prominence so the ships can run on ethane as well as conventional fuel. The work, to be executed alongside yard activity at Cosco Shipping Heavy Industries in Nantong, extends a retrofit model first proven on Navigator Aurora in 2018, with the next project planned to start in early 2027 as part of the owner’s programme to improve fleet efficiency on ethane-linked routes.
What it means for owners
For gas carrier owners, this is a commercially disciplined decarbonisation move rather than a headline-grabbing fuel transition. Ethane-capable propulsion makes particular sense in a niche segment where the vessel is already carrying the fuel it can consume. That changes the economics materially: instead of relying solely on compliant bunker procurement, the ship can monetise cargo boil-off as an energy source, lowering fuel purchase requirements and reducing the operational penalty associated with managing evaporated cargo. On ethane-heavy employment, that can improve voyage margins while also cutting tank pressure management complexity. In an environment where owners are balancing time-charter returns against rising regulatory costs, the ability to displace purchased fuel with cargo-derived energy becomes strategically valuable.
The timing also matters. By 2027, owners trading into Europe will face the combined effect of IMO carbon intensity pressure, EU ETS exposure and FuelEU Maritime compliance economics. Even if an ethane conversion does not transform a vessel into a zero-carbon asset, reducing conventional fuel burn can still improve the emissions profile per transport work and help defend CII ratings, especially on vessels whose trading pattern and cargo mix support regular gas-mode operation. Lower CO2 emissions translate into reduced EUA exposure on covered voyages, and any reduction in fossil bunker consumption may also soften FuelEU compliance costs depending on the fuel pathway and verified performance. For operators of medium gas carriers, this type of targeted retrofit can therefore be more rational than waiting for a future fuel ecosystem that remains commercially immature or regionally unavailable.
There is also a fleet management message in the execution model. Choosing a proven engine platform and repeating an earlier conversion lowers technical uncertainty compared with first-of-type retrofits. Eight years of service experience gives the owner a real operating dataset on reliability, crew familiarity, maintenance intervals and fuel flexibility. That matters because retrofit capex is only justified if the vessel has enough remaining trading life and utilisation in the relevant cargo segment to earn back the investment. Owners considering similar projects will be looking at drydock alignment, class approval lead times, spare parts support, software and control system modifications, and the opportunity cost of off-hire. A conversion tied into planned yard attendance can materially improve the business case by containing downtime. However, yard slots in Asia for technically involved retrofits remain competitive, and engine-house support capacity is now a real gating factor as operators pursue multiple compliance and efficiency projects at once.
MaritimeNG — critical view
The strategic logic is sound, but it is not automatically transferable across the wider gas carrier market. The value of an ethane conversion depends heavily on trade pattern discipline. If these ships spend meaningful time outside ethane service, the economics become less compelling because the retrofit’s fuel-cost advantage falls away while the owner still carries the capex, engineering complexity and downtime burden. In other words, this is a high-conviction optimisation for a specialised employment profile, not a generic decarbonisation template.
There are also unanswered questions around full-cycle returns. The announcement does not indicate expected payback, total project cost, off-hire duration, or whether further efficiency upgrades will be bundled into the yard stay. Tier II compliance may be sufficient for the intended trades, but owners with broader exposure will still have to think about future NOx, methane-slip scrutiny where relevant, and whether investing in mid-life conversions today could constrain later choices on deeper decarbonisation. For some operators, the better capital allocation may still be selective renewal or chartered-in tonnage rather than bespoke retrofit work on older ships.
Verdict
This is a pragmatic, trade-specific retrofit decision rooted in operational evidence rather than fuel-fashion signalling. For shipowners, the takeaway is clear: where cargo, engine platform and deployment profile align, targeted conversions can still outperform broader but less certain decarbonisation bets—and execution timing across yards and vendors will be as important as the technology itself.
Fundamental basis
The economic mechanics behind the facts above, grounded in Martin Stopford’s Maritime Economics. Reference only — not investment advice.
Facing a similar situation on your vessel? Model the numbers before you commit.
Open the off-hire & deviation calculatorsSource Attribution
This analytical review is based on publicly available facts originally reported by Ship & Offshore. MaritimeNG does not claim authorship of the underlying facts. Read the original publication
© 2026 MaritimeNG — Independent analytical commentary. All analysis, opinions, and forward-looking assessments are original work by MaritimeNG Editorial and may differ from those of the parties mentioned or the cited source. Factual data is restated in our own words based on publicly available information. All trademarks and trade names belong to their respective owners. This content does not constitute legal, technical, or investment advice.