Bremerton Upgrade Signals a New Cycle in Naval Yard EPC Demand
The planned modernization at Puget Sound points to a long-duration surge in U.S. naval waterfront engineering rather than a one-off construction package. For maritime EPC firms and fleet stakeholders, the real significance lies in capacity resilience, procurement structure, and the likely knock-on effects across the Pacific maintenance ecosystem.
What happened
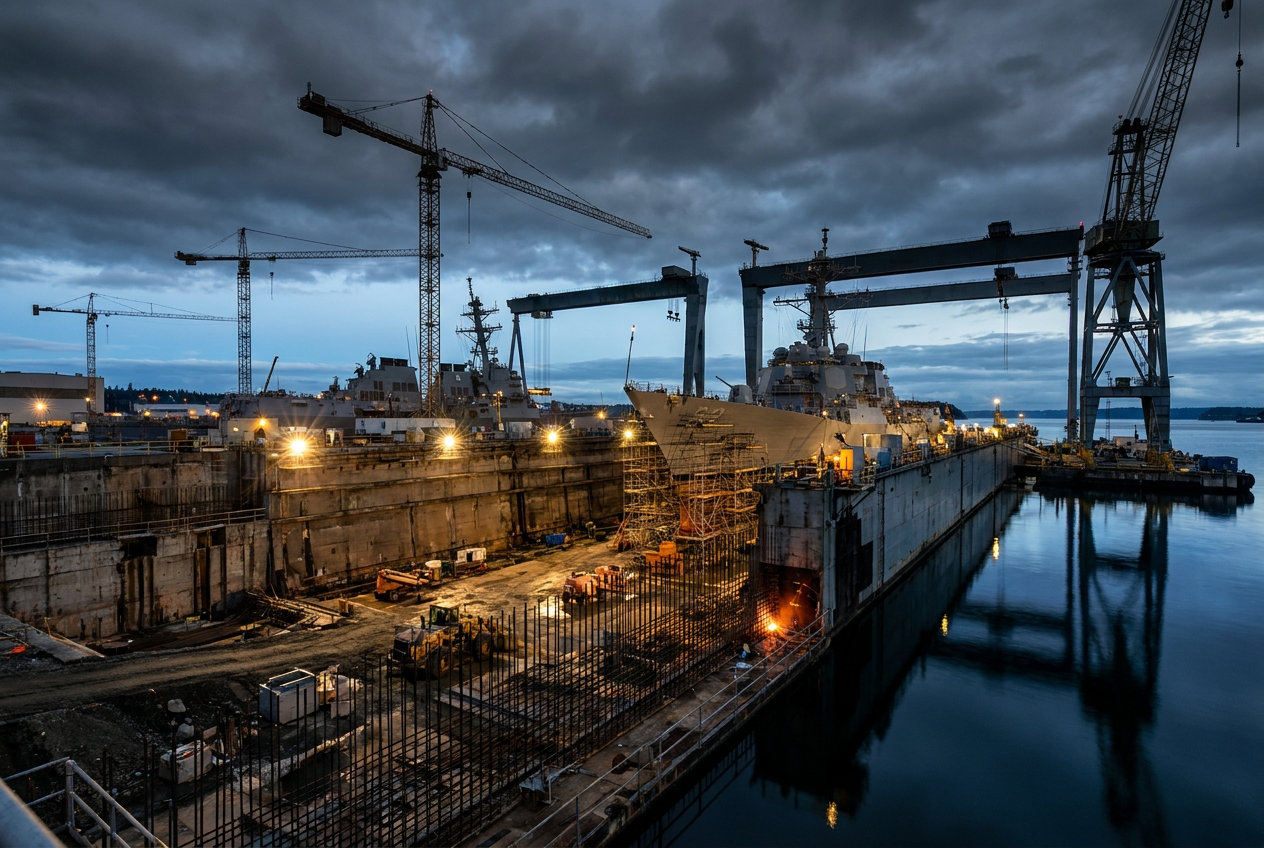
The U.S. Navy is advancing a contractor selection process for a modernization program at the Bremerton yard within Naval Base Kitsap, with a stated value of about $15 billion. The work centers on a new drydock sized for aircraft carriers and associated waterfront, utility, rail, crane, and support infrastructure, alongside demolition and relocation of some existing functions. The contract approach allows as many as five prime contractors, with individual awards starting at no less than $1 billion, and bids are due in early December with selections expected in 2027. Federal estimates indicate construction activity may start around 2030, and the wider public-shipyard recapitalization effort has been assessed by the GAO at roughly $200 billion over several decades.
What it means for owners
For shipowners and operators, this matters less because of the headline project value and more because it addresses a strategic chokepoint in U.S. naval maintenance capacity on the Pacific side. Puget Sound is a critical node for complex carrier and submarine work, and any expansion of drydock throughput can materially affect maintenance backlogs, deployment timing, and the Navy's ability to absorb emergent repairs without disrupting fleet schedules. In practical terms, a larger and better-configured facility should reduce the operational inefficiencies that arise when modern hulls are forced into legacy industrial layouts. Even modest gains in turnaround reliability at a yard of this importance can have outsized readiness effects for the carrier force and attached escort cycles.
For the EPC market, the structure of the procurement is arguably as important as the scope. A multi-prime model distributes risk, broadens access to specialist contractors, and reflects the reality that this is not a conventional vertical-build job but a systems-heavy marine industrial redevelopment program. Drydock civil works, utility resilience, nuclear-support interfaces, waterfront geotechnics, heavy lift logistics, and rail integration all sit at the intersection of maritime engineering and national-security infrastructure. That combination narrows the field to firms with balance-sheet strength, security compliance capability, and experience coordinating live-site construction around mission-critical operations. It also creates a strong pipeline for subcontractors in dredging, electrical distribution, flood-control systems, industrial controls, marine concrete, and fabricated steel. Across the region, this may tighten labor availability and raise competition for specialized trades already in short supply.
There is also a wider competitive implication. U.S. naval shipyard renewal is becoming a sustained industrial theme comparable to major port gateway redevelopment, except with higher technical barriers and longer planning horizons. Contractors that establish performance records on this program may gain an advantage on future public-yard packages at other naval facilities. That could reshape the upper tier of the maritime EPC market over the next decade, with a handful of firms emerging as repeat integrators for defense waterfront assets. Suppliers of pumps, caisson systems, power distribution equipment, crane infrastructure, and digital asset-management platforms should also view this as a demand signal extending beyond one site.
MaritimeNG — critical view
The main risk is not whether funding can be announced, but whether sequencing can be managed without undermining current yard output. Large brownfield naval projects are notoriously vulnerable to scope migration, unforeseen subsurface conditions, utility conflicts, permitting delays, and inflation in materials and labor. In a live naval environment, those standard risks are amplified by security constraints and the operational requirement to keep maintenance work moving while major reconstruction unfolds nearby. If phasing is poorly executed, short-term disruption could erode some of the readiness benefits the investment is supposed to deliver.
Another issue the market should watch is whether program governance can keep pace with the scale of ambition. A project of this type can drift if design packages, site-enabling works, and industrial-relocation tasks are not tightly synchronized. The long runway to physical construction also introduces policy risk: budget reprioritization, changing fleet plans, or revised technical requirements could alter scope before ground is broken. For smaller regional firms, the opportunity is real, but access will depend on how effectively primes structure supply chains, break out work packages, and maintain realistic commercial terms. That is where disciplined market intelligence and contractor-positioning work will matter most.
Verdict
Bremerton is best read as an early marker of a prolonged U.S. naval infrastructure build cycle, not a standalone megaproject. The winners will be contractors and suppliers that can navigate complex marine phasing, defense-grade compliance, and long-horizon capacity planning—an area where close tracking of maritime EPC developments will be increasingly valuable.
Fundamental basis
The economic mechanics behind the facts above, grounded in Martin Stopford’s Maritime Economics. Reference only — not investment advice.
Facing a similar situation on your vessel? Model the numbers before you commit.
Open the off-hire & deviation calculatorsSource Attribution
This analytical review is based on publicly available facts originally reported by The Maritime Executive. MaritimeNG does not claim authorship of the underlying facts. Read the original publication
© 2026 MaritimeNG — Independent analytical commentary. All analysis, opinions, and forward-looking assessments are original work by MaritimeNG Editorial and may differ from those of the parties mentioned or the cited source. Factual data is restated in our own words based on publicly available information. All trademarks and trade names belong to their respective owners. This content does not constitute legal, technical, or investment advice.