Antin’s Vigor Deal Signals Tougher Competition for U.S. Repair Capacity
Antin Infrastructure Partners’ purchase of Vigor Marine Group is more than a change of ownership: it is another sign that investors see strategic value in U.S. ship repair capacity as naval demand rises. For operators, the deal points to tighter repair-slot competition, sharper pricing discipline and a more infrastructure-style approach to yard expansion on the Pacific coast.
What happened
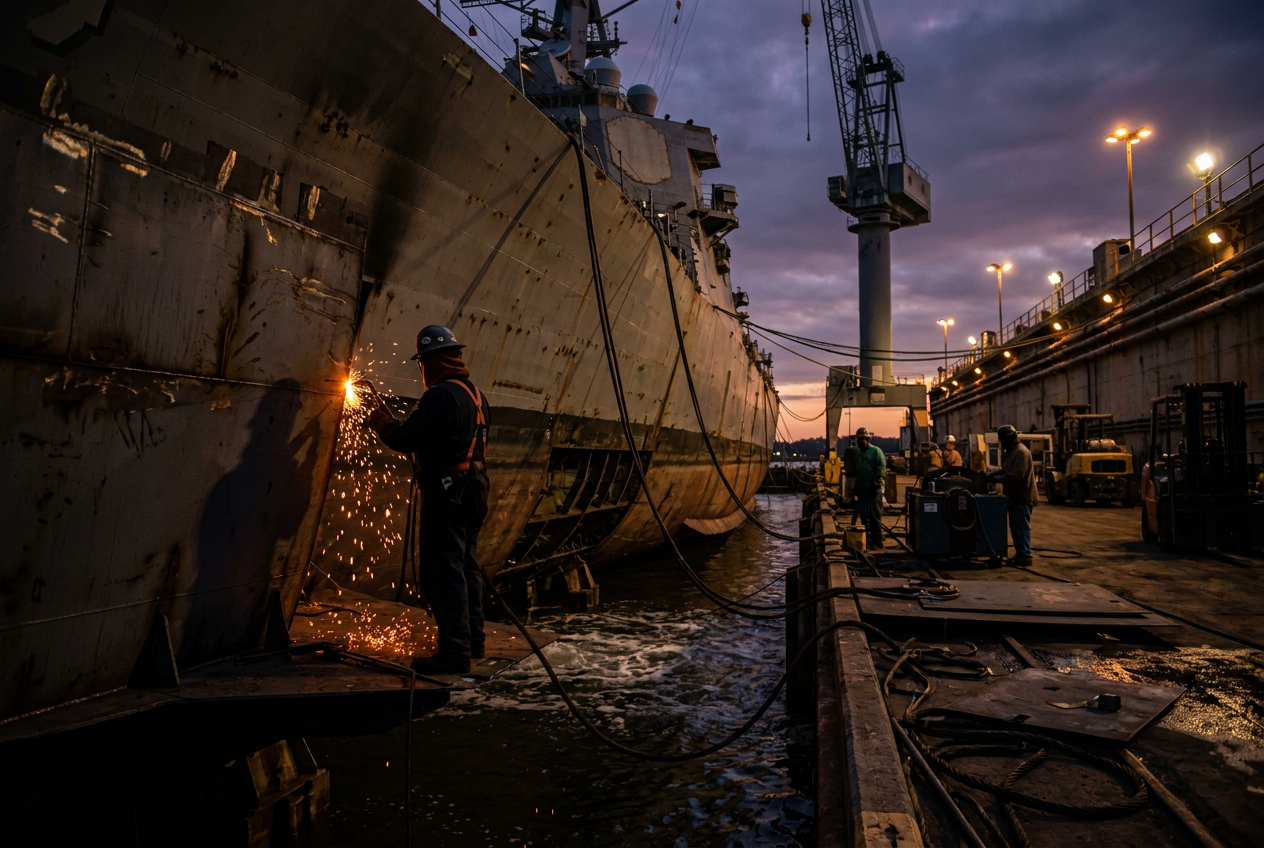
Antin Infrastructure Partners has finalized its takeover of Vigor Marine Group, a major U.S. ship repair and fabrication business headquartered in Portland, Oregon. The company runs yards in Seattle, Portland, Vancouver, San Diego and Norfolk, supported by six drydocks and 29 berths, employs about 2,700 people and generated more than $1 billion in 2025 revenue. The business, now entering its third period under private equity control, was assembled in its current form after Lone Star’s 2023 combination of Vigor Industrial with MHI Holdings in Norfolk and Continental Maritime in San Diego. Antin has framed the acquisition around Pacific coast expansion and a broader U.S. infrastructure investment strategy, while management has emphasized modernization and new technology.
What it means for owners
For shipowners and operators, the most immediate significance is not ownership branding but what this says about the U.S. repair market’s structural tightness. Investors are committing capital because quality waterfront industrial assets with naval relevance are scarce, difficult to replicate and increasingly strategic. That matters commercially because yard access in the U.S. has already been constrained by limited drydock availability, labor bottlenecks and environmental permitting barriers that slow greenfield development. When capacity is scarce, off-hire economics become more punitive for vessel operators: every extra day waiting for a berth, labor gang or docking window compounds charter disruption, schedule slippage and knock-on logistics costs. A larger, better-capitalized Vigor could improve throughput over time if capital is deployed intelligently into docking assets, workflow digitalization and labor productivity. But in the near term, stronger investor interest usually confirms that capacity will remain tight enough to preserve pricing power.
The second-order issue is slot allocation. Vigor’s footprint spans regions where naval work and commercial repair often compete for the same finite infrastructure. With the U.S. Navy and Coast Guard pursuing fleet growth and sustainment, military work offers long-duration visibility, lower counterparty risk and politically supported spending. From a yard operator’s perspective, that can justify major capex. From a commercial client’s perspective, however, it can mean reduced flexibility, longer lead times and a more selective booking environment, especially for lower-margin merchant work. Owners of Jones Act vessels, offshore support tonnage, government-contracted ships and coastal commercial fleets should expect scheduling discipline to tighten further if naval availabilities expand. Commercial operators may need to lock in windows earlier, accept less favorable timing or diversify yard relationships across regions rather than relying on a single preferred facility.
This transaction also reinforces a broader shift in how maritime infrastructure is being valued. Private equity ownership in ship repair used to be viewed largely through a cyclical, turnaround lens. Increasingly, investors are treating strategic yards more like essential infrastructure: scarce assets with regulatory barriers, sticky demand and a quasi-sovereign demand anchor through defense work. That framing can be positive if it brings patient capital for dock upgrades, berth utilization improvements, fabrication capacity and workforce development. Yet private equity still operates on ownership cycles, and each transition creates pressure to demonstrate margin expansion, capital discipline and a credible growth story before the next exit. For customers, that often translates into firmer commercial terms, closer scrutiny of project profitability and potentially less tolerance for complex, disruption-prone jobs that tie up constrained capacity without adequate returns. In practical terms, commercial owners competing with Navy work may face a market where the best yards are financially stronger but commercially less accommodating.
MaritimeNG — critical view
Repeated private equity ownership is not automatically negative, but it does raise a legitimate question about strategic continuity. Ship repair is not software: asset life, dock modernization, apprenticeship pipelines and waterfront permitting all require long horizons. If ownership keeps changing every few years, there is a risk that investment decisions favor valuation optics over the slower, harder work of expanding real capacity. The industry has seen cases where consolidation improves procurement and management discipline without materially solving berth scarcity or labor shortages. For commercial clients, the danger is that stronger financial stewardship coexists with a market that becomes more expensive, less flexible and more segmented by customer type.
There is also a concentration risk in the Navy-led investment thesis. Defense demand is a powerful tailwind today, but it can also distort incentives. If too much capital is underwritten on the assumption of sustained military work growth, commercial ship repair customers may end up subsidizing underutilized periods through higher prices, or conversely be crowded out during peak naval demand. Political support for fleet expansion is real, but budget cycles, program delays and policy changes can alter yard utilization patterns quickly. The most durable strategy will be one that expands productive capacity across both defense and commercial segments rather than simply reprioritizing who gets access first.
Verdict
Antin’s acquisition strengthens the case that U.S. ship repair has become a strategic infrastructure asset class, not just a cyclical maritime service business. That should support investment and modernization, but for shipowners the practical takeaway is more immediate: secure repair slots earlier, expect tougher commercial discipline and monitor how defense demand reshapes yard access across key U.S. coasts.
Fundamental basis
The economic mechanics behind the facts above, grounded in Martin Stopford’s Maritime Economics. Reference only — not investment advice.
Facing a similar situation on your vessel? Model the numbers before you commit.
Open the off-hire & deviation calculatorsSource Attribution
This analytical review is based on publicly available facts originally reported by The Maritime Executive. MaritimeNG does not claim authorship of the underlying facts. Read the original publication
© 2026 MaritimeNG — Independent analytical commentary. All analysis, opinions, and forward-looking assessments are original work by MaritimeNG Editorial and may differ from those of the parties mentioned or the cited source. Factual data is restated in our own words based on publicly available information. All trademarks and trade names belong to their respective owners. This content does not constitute legal, technical, or investment advice.